UK vehicle production jumps 36.3% in September
UK vehicle production jumped 36.3% in September to 74,031 units, according to figures the Society of Motor Manufacturers and Traders (SMMT) published today. It is the strongest growth since August 2022. The rise reflects last year’s unprecedented cyber incident, which halted production at Britain’s biggest automotive employer.
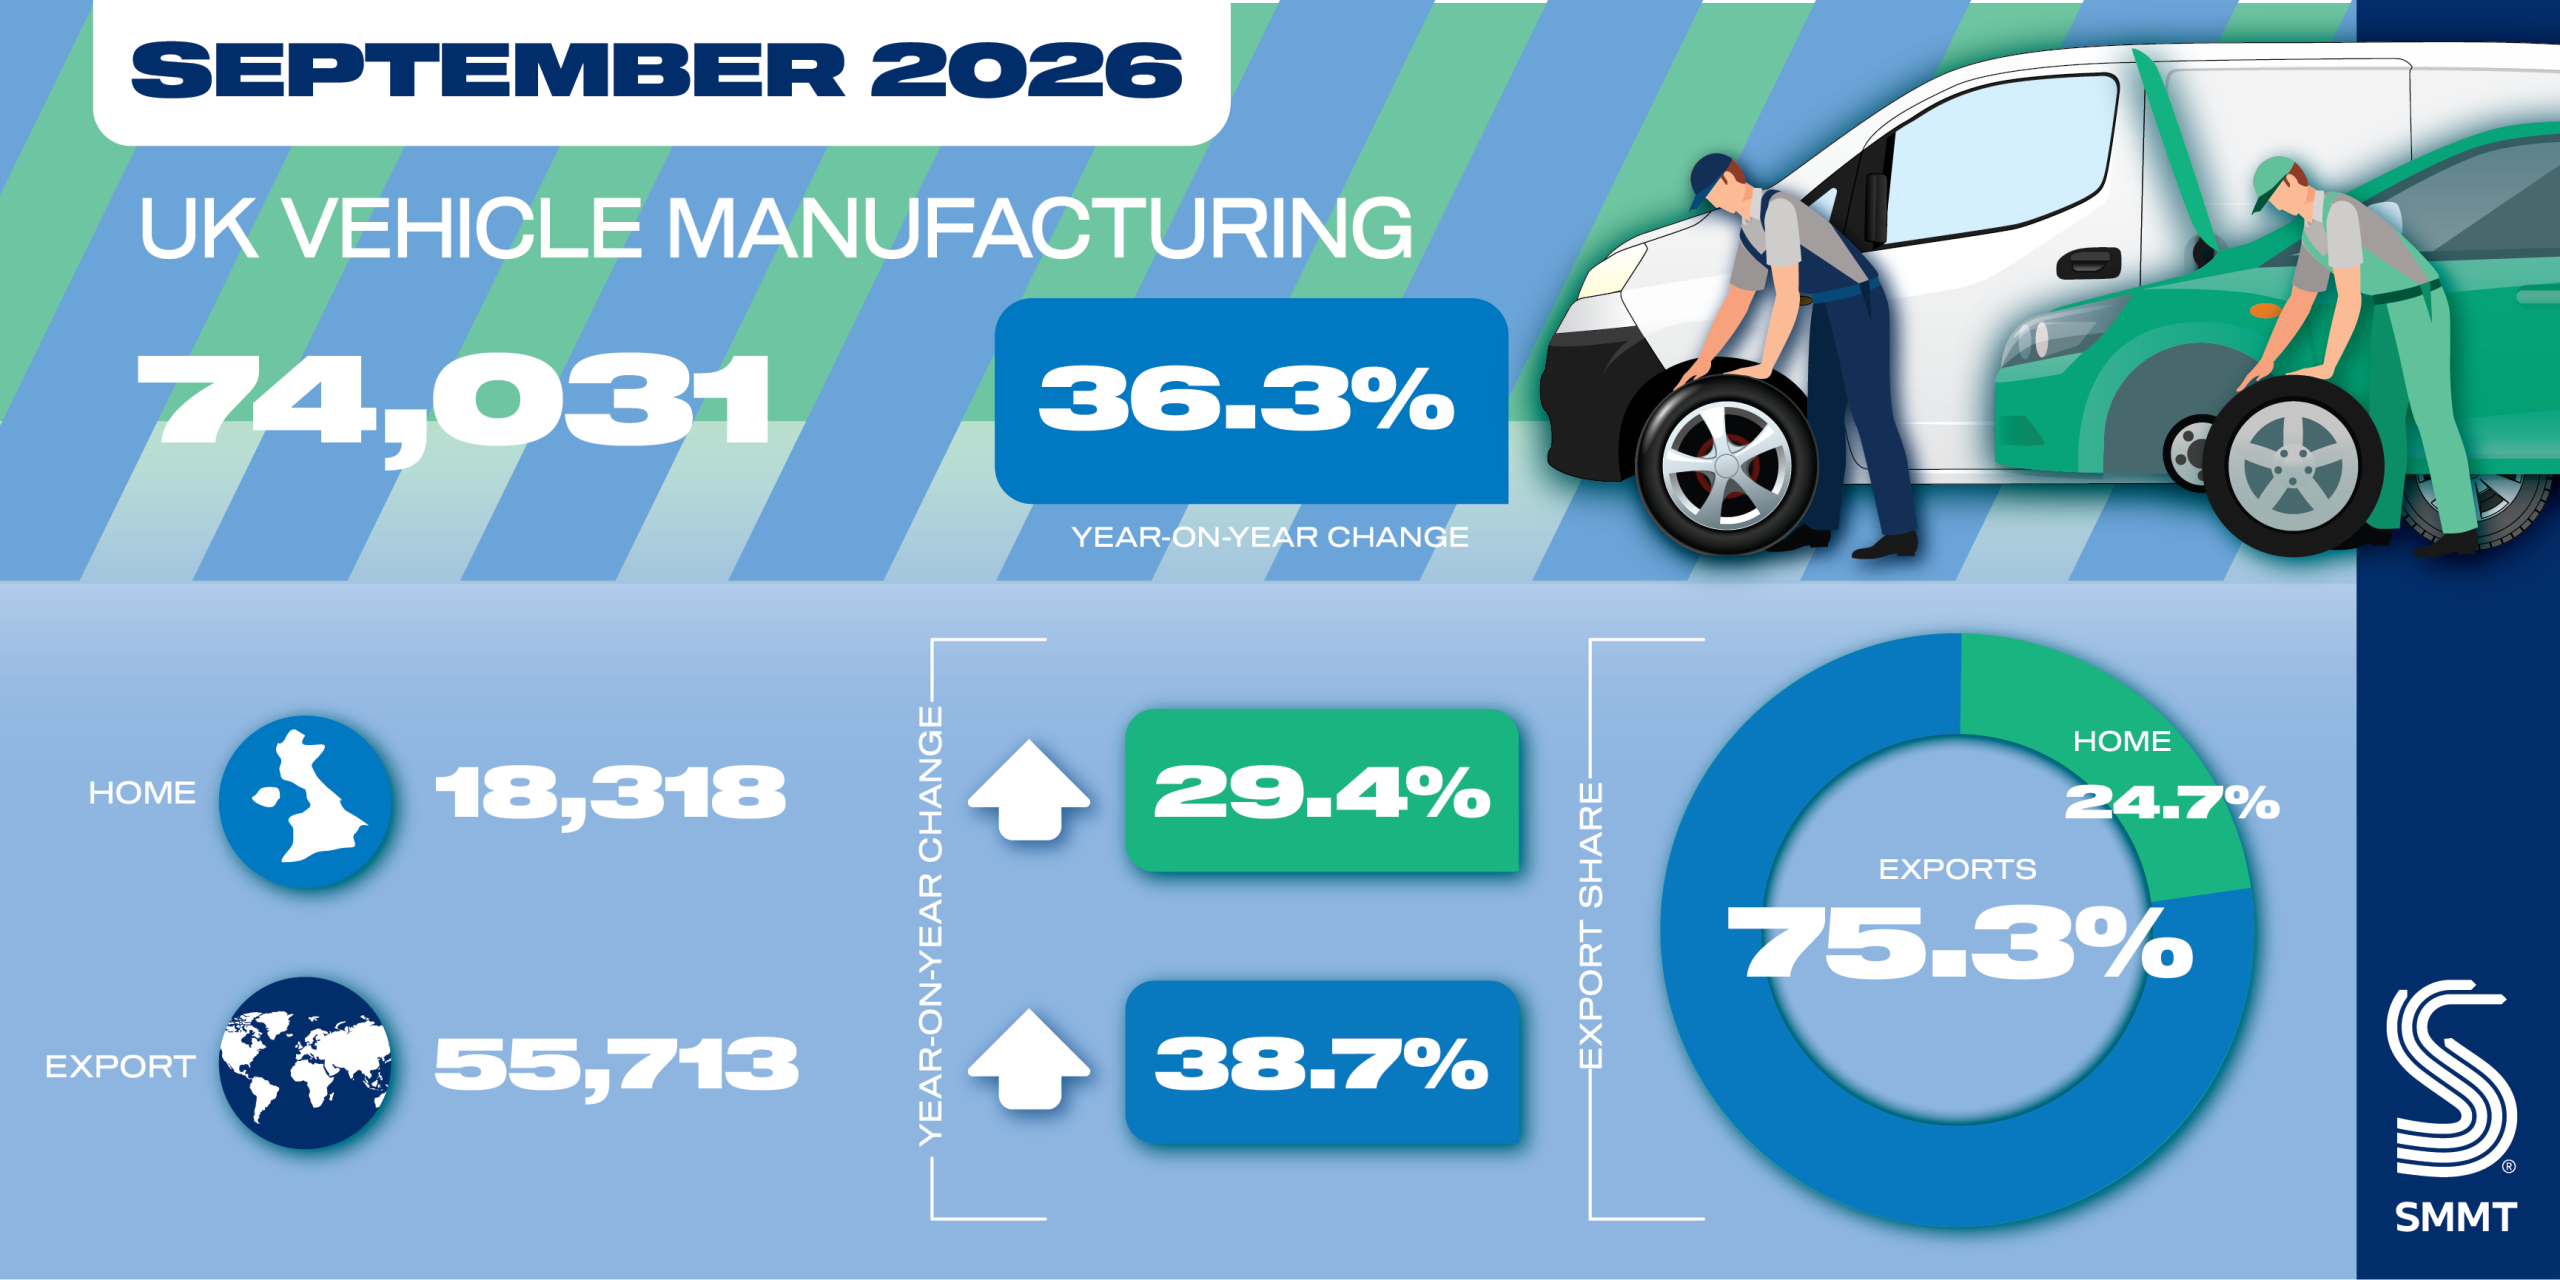
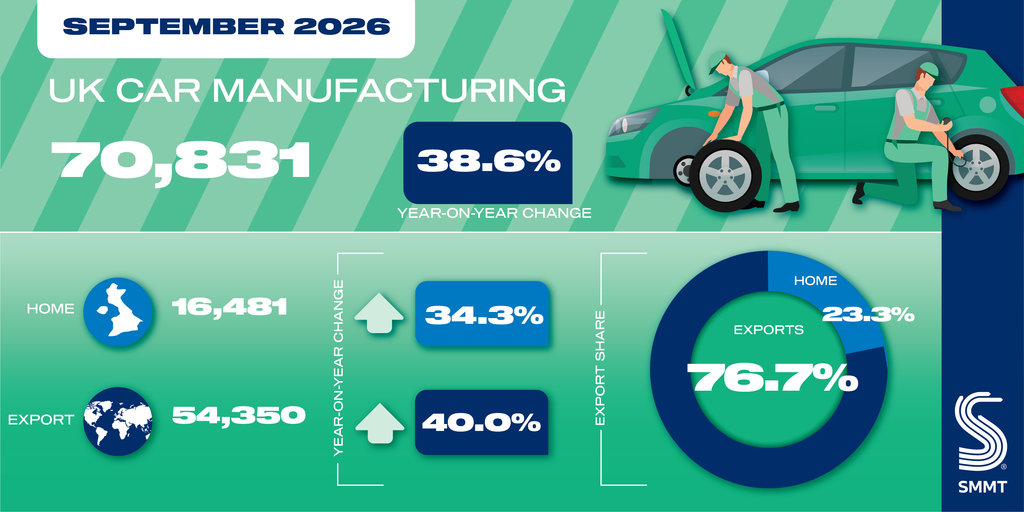
Car output climbed 38.6%, with 70,831 vehicles leaving factory lines. That makes it the best September for UK car manufacturing since 2023. Electrified models helped drive the increase. Their output rose 22.5%, and they made up 42.3% of all cars built in the month, as well as 70.1% of exports. Exports still account for more than three quarters of production, with 76.7% of cars heading overseas.
Exports to China and the US surge
Shipments to the UK’s three biggest automotive markets all rose sharply. China led the way with a 357.7% increase, although from a low base, giving it a 4.4% share. The US grew by 234.8% and took 16.8% of the total. The EU remained the largest destination, receiving 57.5% of exports, with volumes up 12.7% year on year.
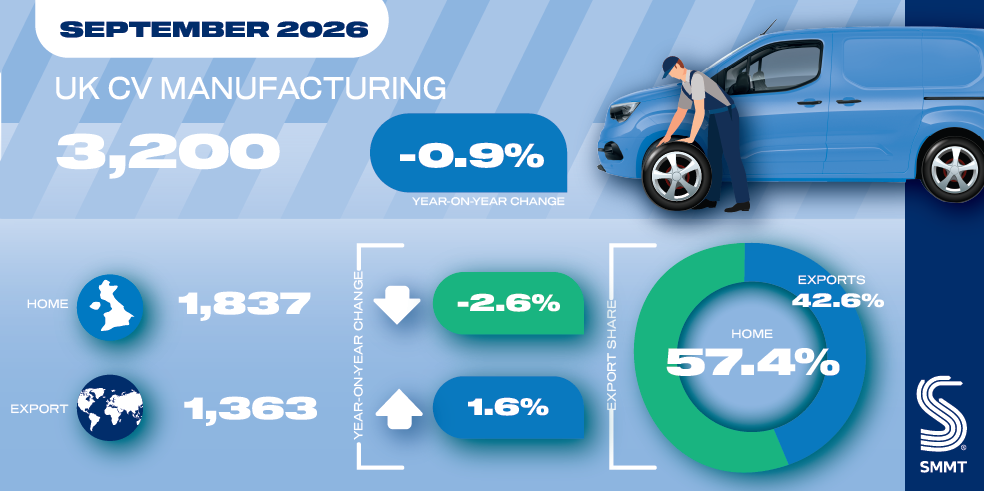
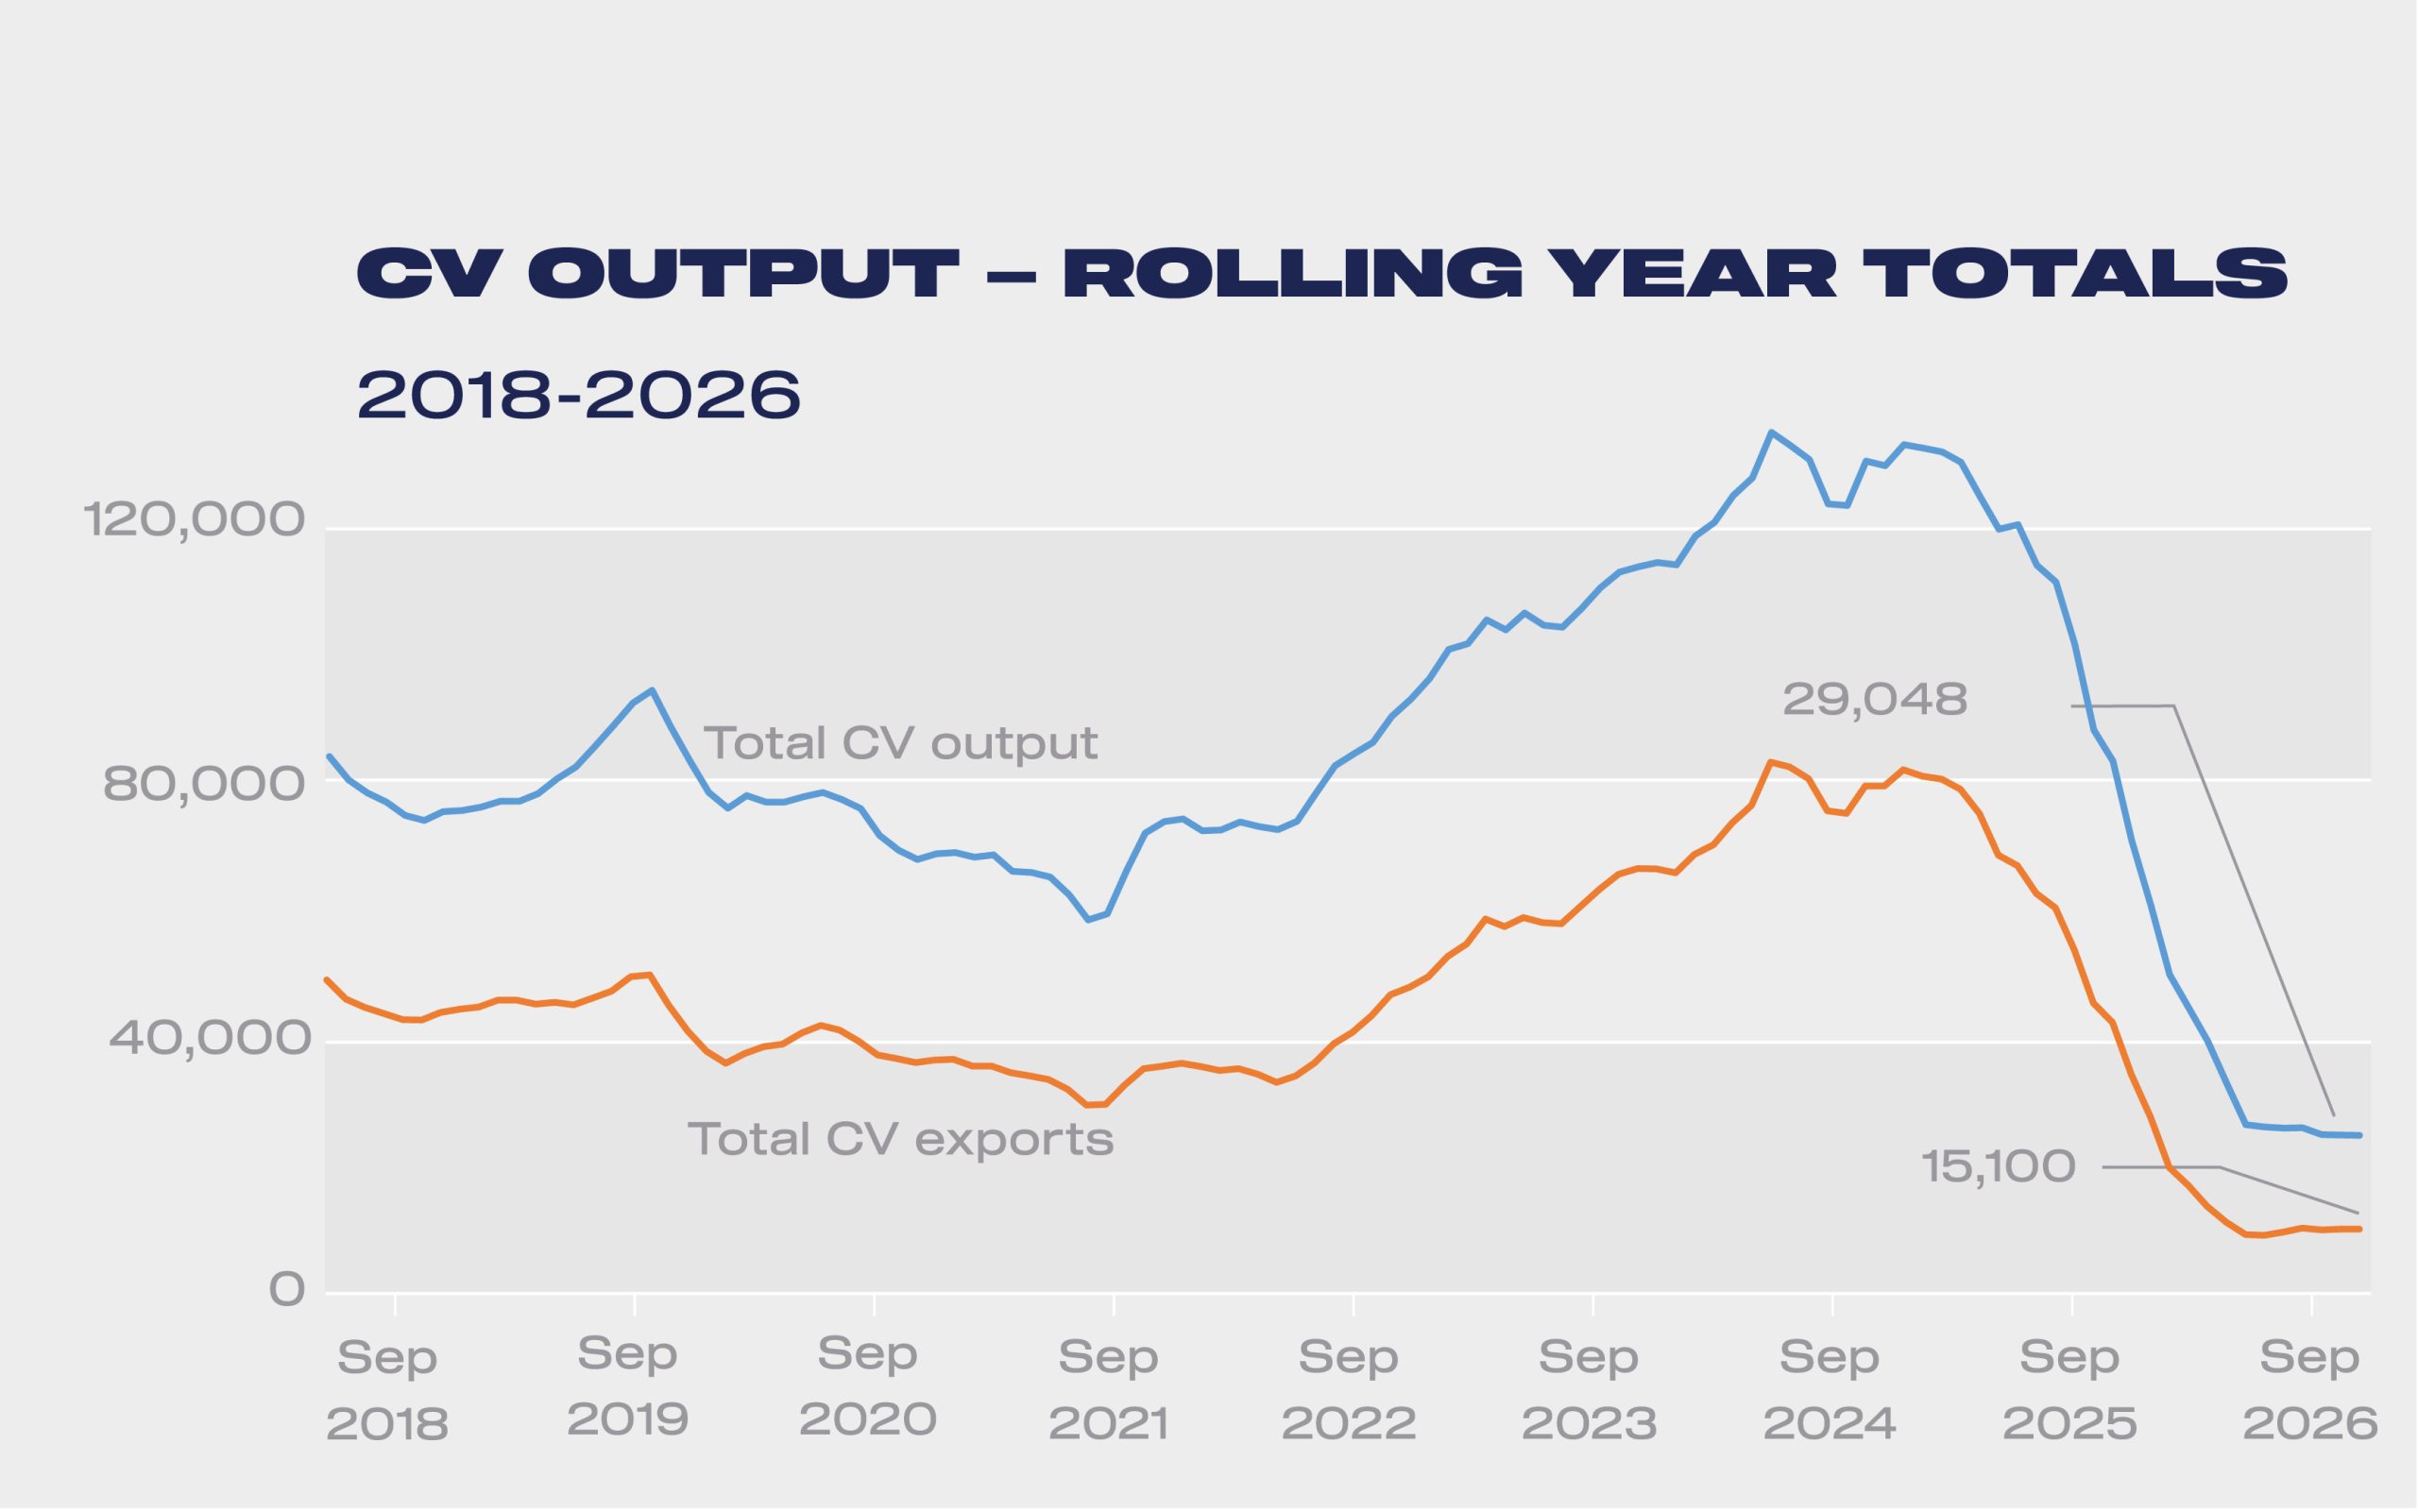
Commercial vehicle (CV) exports also grew, rising 1.6%. However, output for the domestic market fell 2.6%, so overall CV production slipped 0.9%. Year-to-date performance remains down 46.7% following structural changes within the sector.
Full-year outlook remains subdued
Across the first nine months, UK factories built 564,537 cars and CVs, a decline of 3.0% year on year. An independent outlook expects light vehicle output of 731,000 units for the full year. That is 2.3% lower than in 2025 and below the mid-year forecast, as model changeovers continue. Forecasters expect a recovery to 752,000 units in 2027 as new models, mostly electric, enter production.
Three threats to UK automotive competitiveness
Three major threats to UK competitiveness put that recovery at risk. The first two come from the UK’s relationship with Europe. The European Commission’s ‘Made in EU’ proposals would, as drafted, effectively exclude UK-built vehicles from their largest market.
Tougher rules of origin under the Trade Cooperation Agreement, known as the Brexit deal, add further risk. From 2027, they could trigger a shared annual £1.4 billion tariff bill on EV trade in both directions. Both measures would damage industry on both sides of the Channel. The forthcoming EU-UK Summit is therefore a vital chance to agree pragmatic solutions and safeguard an €80 billion trading relationship.
The third threat is closer to home. Unrealistic EV sales targets are putting manufacturers under acute pressure. They erode profitability, divert resources and weaken the UK’s appeal as an investment destination. The industry has backed the shift to electric vehicles, committing at least £14.3 billion to new EV plants and models since 2020. It is also investing billions more in discounts and incentives to sell them. Those funds would be better spent on new products, manufacturing competitiveness and cyber security, which last year’s events and more recent disruption have put into sharp focus.
ZEV Mandate review must deliver reform
The sector directly supports 188,000 British jobs and contributes £18 billion to the economy each year. The ZEV Mandate review must therefore align the EV trajectory with the government’s industrial and growth ambitions. Meaningful reform will deliver reindustrialisation as well as decarbonisation.
Mike Hawes, SMMT Chief Executive, said, “September’s rebound is welcome, but comparison with last year’s disruption masks the pressures on UK manufacturing. Protectionism is becoming a feature of global trade, and that threatens not just UK automotive as an export-led sector, but the health of industries overseas as well. Pragmatic discussions with trade partners are required but Government can immediately help the industry with an urgent conclusion to the ZEV Mandate review. Mandate targets are running ahead of demand and draining resources required for British factories and jobs. Substantive changes – not marginal adjustments – are needed to ensure decarbonisation does not come at the cost of reindustrialisation.”